Financing a home is about far more than interest rates.
Story by Tracy Dickinson
Featured in Autumn 2026
Because interest rates can have such an effect on the cost of buying a home, it’s easy to get hyperfocused on that number. And after the phenomenally low rates during the COVID years, it might be tempting to think those numbers or something close will return if you just wait a little bit longer.
But that singular focus ignores several other factors that are just as significant in the home-buying decision. Financial experts advise looking at the entire package, not just the rate, if you’re debating whether now is the right time to buy.
Shop around.
Most lenders, including online sources, will offer comparable or matching rates, but they often differ dramatically in other areas.
GreenState’s Kurt Backes says, “I encourage potential borrowers to shop around, but it’s important to explain that one number isn’t the entire story. You have to look at APR (annual percentage rate), as well as other costs and fees. Sometimes, to offer a lower interest rate, lenders will charge additional fees or add hidden costs, so the loan ends up costing the borrower more.”
Cassandra Haller of Bankers Trust says, “The ups and downs of the past few years have made homebuyers savvier. We’ve been very busy this year. In general, borrowers are more disciplined and buying within their means. Watching the activity over the last couple of years has helped people shop smarter.”
Another advantage to shopping around is the opportunity it provides to get to know potential lenders.
“The cliché that ‘you shouldn’t marry the interest rate—marry the house’ is really true. If you’re in a position to buy, the interest rate shouldn’t be holding you back.”
Kurt Backes, GreenState
“Anyone can match a rate, usually,” says Bankers Trust’s Mindy Selix. “But you want to work with someone who is advocating for you, who communicates well, and is going to take care of you.” She says not every lender has access to the same financial programs, so partnering with an institution approved for a variety of grant and lending programs can make a huge difference in the mortgage options available to you.
“Different programs have different requirements,” Haller says, “and the right lender will walk you through those options. Some federal programs are income-based, and here at Bankers Trust we offer a number of our own in-house financing options.”
Backes says, “It’s important to sit down and talk with lenders to find out your options. GreenState has in-house financing that could be a better fit than what you can find just looking at rates.”
Focus on the total.
“The cliché that ‘you shouldn’t marry the interest rate—marry the house’ is really true,” says Selix. “If you’re in a position to buy, the interest rate shouldn’t be holding you back.”
Haller says, “There is always something affecting rates. And they tend to drop slower than they rise, so waiting on the rate specifically may not be the best approach. The total monthly payment is a better number to focus on.”
Assessing how much you are comfortable paying monthly and working backward from there can give you a more realistic picture of what you can actually afford.
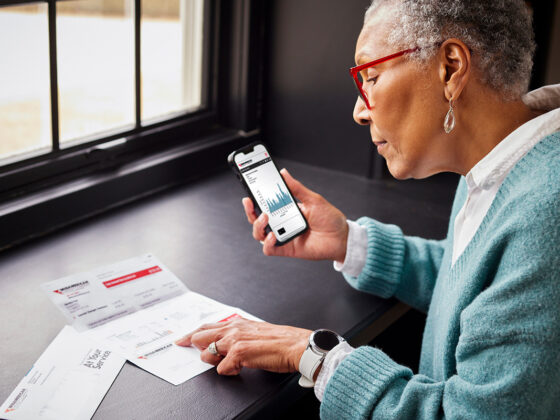
“I always advise clients to start with the monthly payment, not the interest rate,” Backes says. “There are so many other costs involved in owning a home that it’s important to walk through those with that monthly payment in mind.”
Yes, you can use an online mortgage calculator to tell you what the monthly payment would be on $350,000 at 6% interest. But that’s just a small part of the picture. In addition to home insurance, property taxes, and possibly PMI (private mortgage insurance), you need to consider the cost of utilities, any homeowners association (HOA) fees, maintenance or repair costs, and more.
“What you can get approved for isn’t necessarily the same as what you should budget for a monthly payment,” Selix says. “That’s another reason to have a lender who’s advocating for you.”
Crunch the numbers.
Once you have that monthly budget, take a realistic look at your financial situation.
“You have to ask whether your income matches your expectations,” says Haller. “I make it a point to meet face-to-face with potential clients so I can get to know them and have a good conversation about their current finances and the options available to them.”
If you already own a home, you likely have a better grasp of the costs of financing, and you have equity from your current home as well. But first-time homebuyers may be less prepared for that initial conversation.
“I encourage potential borrowers to shop around,
Mindy Selix., Bankers Trust
but it’s important to explain that one number
isn’t the entire story.”
“There are three factors to consider,” says Backes. “Those are income, down payment, and credit history. It’s worthwhile to sit down with a lender now if you’re a first-time homebuyer looking at purchasing a year or so down the road.”
Haller says, “If a potential client doesn’t have any credit history or has issues in their credit history, we can address that and clean up those issues before they’re ready to apply for financing.”
Although credit cards are the surest way to establish a credit history, it’s possible to do so without them, and your lender can provide important guidance on that as well.
Start now.
If you’ve crunched the numbers and are just waiting for interest rates to look more favorable, now might be the time to jump down off the fence.
“Assuming you’re in a position to buy,” says Selix, “waiting can end up costing you more money. Home prices won’t go down, interest rates could increase, and the little you’ll save on a monthly payment waiting for lower interest rates could be lost when prices go up.”
Backes says, “There’s an old saying that the best time to buy was yesterday. Costs to purchase, to finance, to own a home typically just keep going up. But at GreenState we really work to tailor the financing to the borrower to fit both long- and short-term goals.”
Whether you’re buying for the first time, hoping to move up, or building a custom home, the steps to financing that dream are the same. And the interest rate is just part of that package.
Resources
GreenState Credit Union and Bankers Trust Equal Housing Lenders.
- Cassandra Haller NMLS ID#: 681625, Bankers Trust
- Mindy Selix NMLS ID#: 571223, Bankers Trust
- Kurt Backes NMLS ID#: 1083013, GreenState Credit Union